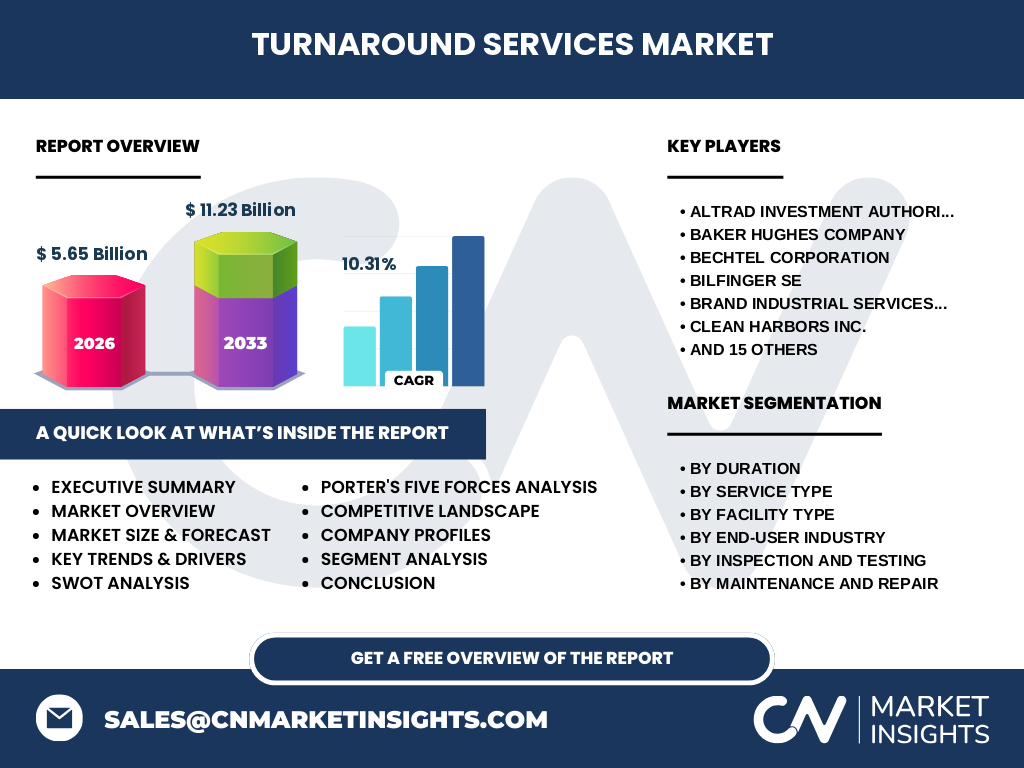
Market overview of the Turnaround Services Market
Our analysis indicates that the Turnaround Services Market is valued at $5.65 Billion in 2026, serving as an indispensable pillar for asset-heavy industrial sectors. These specialized services encompass meticulous planning, heavy maintenance, non-destructive testing, and chemical decontamination required when refineries, chemical plants, and power generation facilities halt operations for scheduled overhauls, ensuring regulatory compliance and asset longevity.
Key market drivers, restraints, challenges, and opportunities shaping the Turnaround Services Market
The market is driven by aging infrastructure and stringent mandates from regulatory bodies like OSHA and the EPA. Growth restraints involve high upfront capital expenditures and production downtime risks. However, opportunities abound in digital twin integration and predictive maintenance, giving firms like Bechtel Corporation and Fluor Corporation a competitive edge in minimizing costly plant outages.
Emerging trends and growth patterns in the Turnaround Services Market
The shift toward automated robotic inspection and advanced chemical cleaning services is redefining turnaround execution. Data-driven scheduling and real-time workforce tracking are replacing traditional manual planning, allowing industrial operators to compress critical path schedules and safely deploy thousands of contractors during complex refinery and offshore platform overhauls.
COVID-19 impact analysis and recovery trajectory
The pandemic forced widespread postponement of non-essential maintenance, creating a massive backlog of deferred capital projects. Recovery has been characterized by an aggressive surge in turnaround frequency, with firms adopting modular execution strategies and stringent on-site health protocols to mitigate contagion risks while executing urgent mechanical and electrical repairs.
Competitive landscape and strategic market concentration
The Turnaround Services Market exhibits a semi-consolidated structure dominated by global engineering giants and specialized maintenance providers. Market concentration is high among top-tier participants who leverage comprehensive service portfolios—spanning from scaffolding by Brand Industrial Services Inc. to metallurgical testing by MISTRAS Group Inc.—to secure enterprise-level master service agreements.
Executive summary of key findings
Our comprehensive research forecasts the Turnaround Services Market to surge from $5.65 Billion in 2026 to $11.23 Billion by 2033. Achieving a robust 10.31% CAGR, the sector is propelled by mandatory emissions compliance, aging chemical processing units, and technological innovations that reduce costly operational downtime across global processing facilities.
Market forecast from 2027 to 2033
Based on our econometric modeling, the market will expand rapidly from its 2026 baseline of $5.65 Billion to reach $11.23 Billion by 2033, registering a notable 10.31% CAGR. This trajectory reflects increasing investments in deepwater offshore platforms, greenfield chemical complexes, and rigorous environmental compliance retrofits globally.
Segmentation analysis by service, duration, and facility type
The market breaks down by duration (Short-Term, Medium-Term, Long-Term Turnarounds), service type (Project Management, Maintenance, Inspection, Cleaning, Replacement, Safety, Recommissioning), and facility type (Refineries, Chemical Plants, Power Plants, Offshore Platforms, Processing Units, Storage Terminals, Pipeline Networks). Each segment plays a vital role in mitigating operational risks across heavy industries.
Regional market analysis and geographic distribution
Geographic performance varies significantly, with North America and the Middle East leading due to dense concentrations of oil refineries and petrochemical complexes. Asia-Pacific represents the fastest-growing frontier, driven by rapid industrialization in emerging economies requiring extensive manufacturing plant maintenance and large-scale power generation overhauls.
In-depth regional review of high-growth territories
North America dominates revenue generation, supported by stringent environmental regulations and aging midstream pipeline networks. Meanwhile, the Middle East showcases high-value long-term turnarounds on massive offshore platforms and processing units, engaging international EPC contractors to execute complex brownfield modifications without compromising active hydrocarbon yields.
Strategic company positioning and market focus
Industry leaders employ distinct strategies: Technip Energies N.V. and Saipem S.p.A. focus on complex offshore and energy transition projects, while Altrad Investment Authority SAS and Bilfinger SE dominate multi-disciplinary industrial maintenance, scaffolding, and insulation services across European and international manufacturing plants.
Porter's Five Forces analysis
Buyer power is moderate-to-high, as major oil and gas operators demand strict cost controls and safety metrics. Threat of substitutes remains low due to the irreplaceable nature of physical maintenance. Competitive rivalry is intense, pressuring margins and forcing firms like Jacobs and KBR Inc. to differentiate via proprietary digital project management platforms.
SWOT analysis of the Turnaround Services Market
Strengths include high technical barriers to entry and sticky client relationships. Weaknesses involve labor shortages and inherent execution hazards. Opportunities lie in digital twins and remote robotics, while threats stem from macroeconomic volatility and sudden shifts in global energy policies.
Value chain analysis from raw materials to end-users
The value chain initiates with specialized software and equipment procurement, flowing through engineering design, labor recruitment, and on-site execution. Value accumulates during the critical path execution phase, ultimately delivering operational integrity and extended asset life to end-users in oil and gas, power generation, and fine chemicals.
Investment insights and strategic high-potential areas
High-potential investment pockets lie in specialized non-destructive testing, automated chemical cleaning, and proprietary scheduling software. Strategic investors should target mid-sized engineering firms possessing specialized safety certifications and workforce deployment capabilities to capture outsized gains in the expanding maintenance landscape.
Conclusion and key takeaways for industry stakeholders
The Turnaround Services Market offers exceptional growth potential, reaching $11.23 Billion by 2033 at a 10.31% CAGR. Success hinges on adopting advanced inspection technologies, maintaining impeccable safety records, and leveraging digital tools to compress turnaround schedules and maximize refinery and chemical plant profitability.
Research methodology and data triangulation
Our baseline estimates are rigorously triangulated by combining primary stakeholder interviews with C-level executives, secondary macroeconomic data from trade registries, and proprietary bottom-up market sizing models. This multi-layered approach ensures precise quantification of segment revenues across refineries, power plants, and chemical processing complexes.
Scope of the report and coverage parameters
This report covers global market dynamics for turnaround services from 2026 to 2033, evaluating multiple facility types, service categories, and end-user industries. Limitations include unforeseen geopolitical disruptions and sudden macroeconomic shifts that could temporarily alter capital expenditure allocations for scheduled plant maintenance.
Recent developments, partnerships, and strategic moves
Recent market activity highlights increased joint ventures between digitalization specialists and traditional maintenance contractors. Companies such as Baker Hughes Company and John Wood Group PLC have launched advanced remote monitoring and automated inspection partnerships to enhance efficiency during critical petrochemical turnaround windows.